|
Cost Segregation for Commercial & Short-Term Rental Owners
|
Request a free estimate [email protected] |
Vacation Markets
Free Listing SEO Audit Paste your Airbnb or VRBO listing. Get a scored audit in 90 seconds. Audit My Listing »FREE Estimate Is there a first-year deduction sitting in your building? No cost, no obligation. Request Yours »Minimum ROIOur study identifies at least 20x its fee in first-year deductions on commercial property, or at least 30x on a short-term rental, or it is free. |
Does Cost Segregation Work on a Coeur d'Alene Rental Property?Quick answer Cost segregation applies to a Coeur d'Alene rental the same way it applies anywhere: an engineering study moves real components, a dock, furnished interiors, outdoor living space, onto faster 5-, 7-, and 15-year depreciation schedules instead of the building's 27.5/39-year one. What sets Kootenai County apart is its single-peak calendar, a concentrated July lake season with quieter shoulder months, which changes how much weight the off-peak bookings carry in the yearly average-stay test. Own a Coeur d'Alene rental? See the first-year deduction range a study would look for. 30 seconds, no email to see the range. Start the check ↓Key takeaways
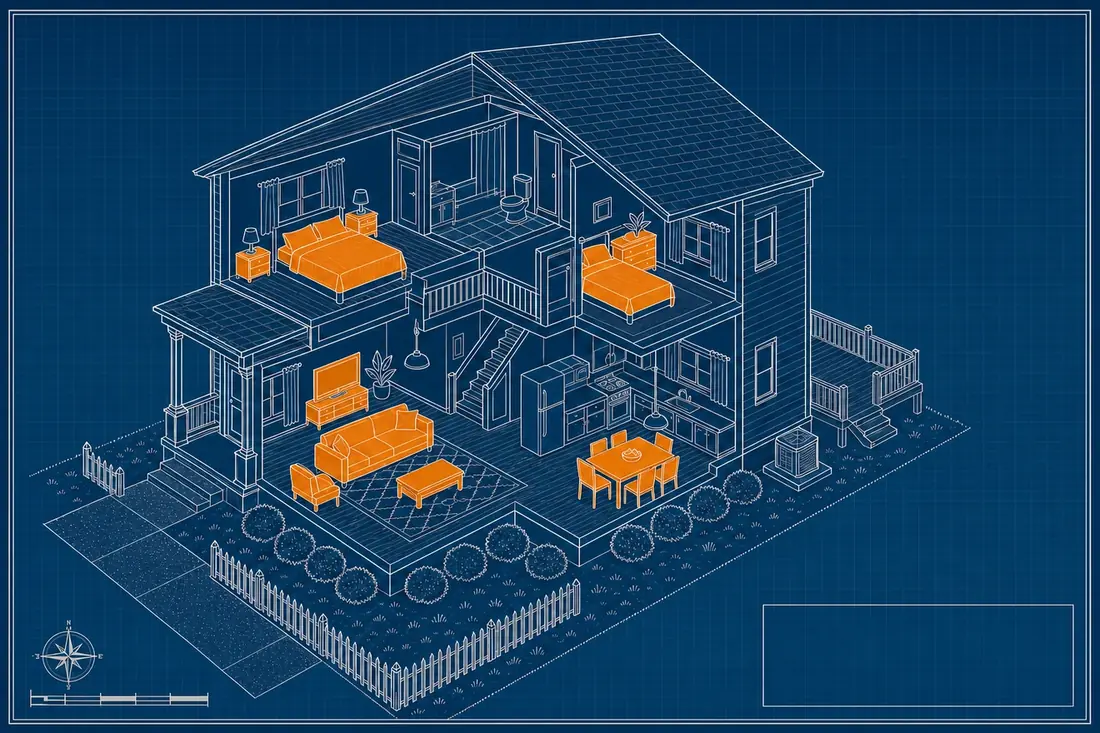
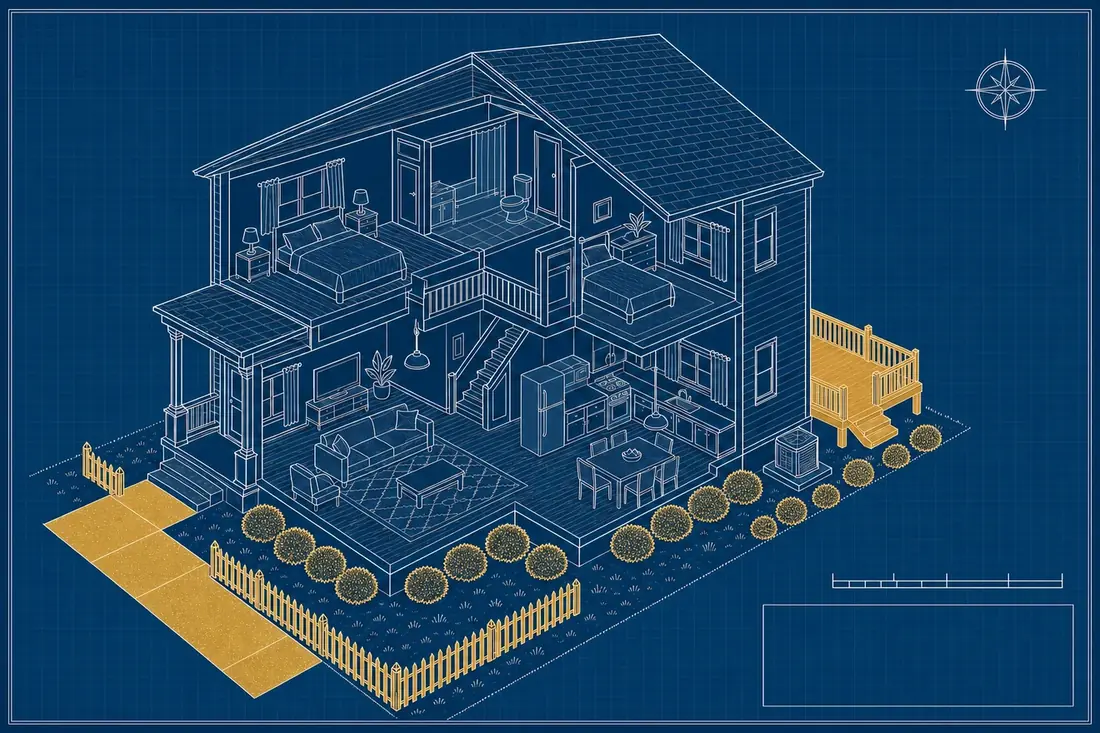
Watch a lake house rental get built and classified A hypothetical $900,000 four-bedroom lake house goes up on a sloping lot, from the driveway and the walkout level to the great room, the screened porch and the covered dock. Every component lands on its depreciation schedule as it is installed, and the year-one depreciation adds up on screen. Watch the 90-second walkthrough »Coeur d'Alene as a rental marketCoeur d'Alene sits in Kootenai County, Idaho, on the lake that shares its name, with Spokane, Washington sitting close enough to feed the bulk of the market's drive-to traffic. The rental stock here runs on a single-season shape rather than the four-season or two-season pattern other vacation markets carry: a concentrated peak built around July's lake weather, with the shoulder months running considerably quieter. That single-peak shape is close to a ski town's opposite, one intense summer window instead of a winter one, and it changes how a property's booking calendar behaves across the tax year compared with a market that spreads its traffic more evenly. The rental stock along the lake runs mostly to single-family lake homes and cabins, with a smaller stock of condos closer to downtown Coeur d'Alene. A lake home comes with its own component list beyond what a standard house carries, starting at the water's edge. Whether the structure itself sits on 27.5 or 39 years turns on the 80% dwelling-unit test, and a short-term rental averaging stays of 7 days or less generally lands on 39 (see the 27.5 or 39 years guide). 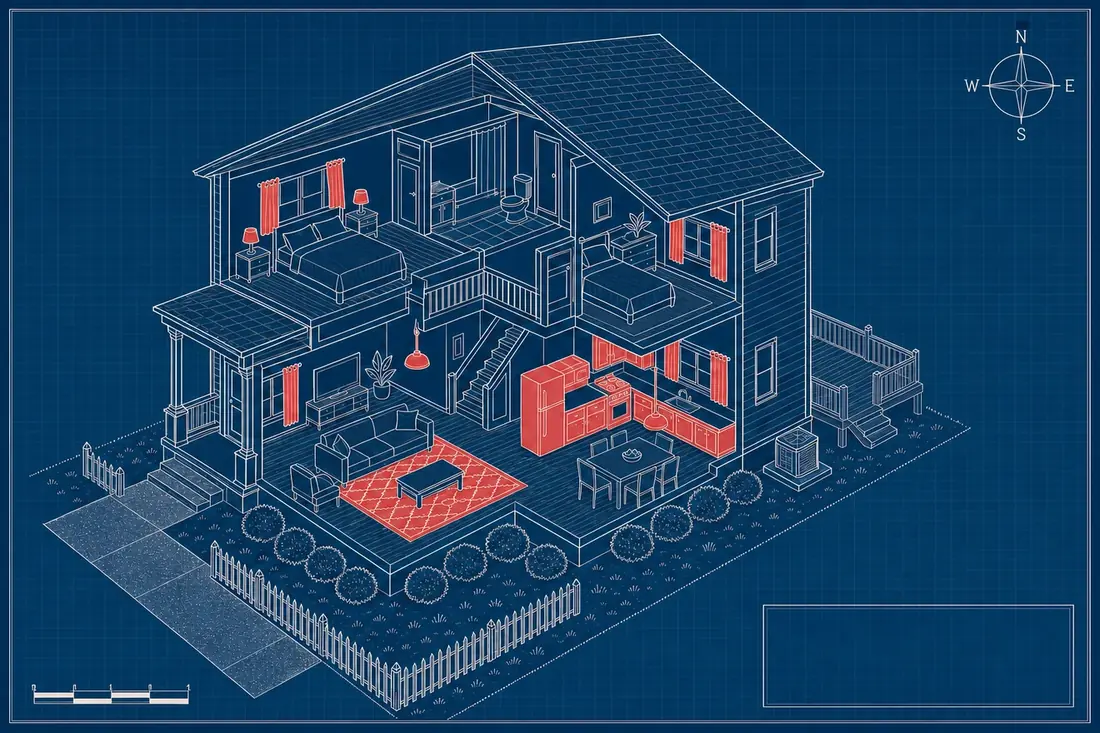
5-Year: carpet and flooring, cabinets, appliances, light fixtures, curtains 7-Year: furniture 15-Year: driveway, fencing, landscaping, deck 27.5/39-Year Shell: roof, load-bearing walls, foundation, central HVAC Get your free Preliminary Benefit Estimate See what a Coeur d'Alene lake property's dock and outdoor components could add up to with the free 60-second estimate at /qualify. Request Your Free Estimate »What a Coeur d'Alene lake rental has to reclassifyA typical lake property here, house or condo, carries components an engineering study can move off the building's 27.5/39-year schedule:
The house's foundation, framing, roof, and any central HVAC stay on the 27.5/39-year schedule regardless of how much lake-specific equipment sits around them, the same structural rule that applies to any residential rental anywhere. One peak month and the 7-day averageA property whose average guest stay across the tax year runs 7 days or less falls under the short-term rental exception in Reg. 1.469-1T(e)(3)(ii), taking it out of the standard passive rental-activity framework under section 469. Coeur d'Alene's single-peak calendar puts a specific kind of weight on that yearly average: with July carrying the bulk of a property's bookings and the rest of the year running quieter, the handful of stays booked outside the peak month can pull the yearly average in either direction more easily than they would in a market with steadier year-round demand. A few longer bookings in the off months can move the average more than the same bookings would on a busier, more evenly spread calendar. Whether the actual mix, July's bookings plus whatever fills the rest of the calendar, lands at or under the 7-day line is a computation run against that specific property's real booking record, not something to assume from the seasonal shape alone. A market like the Vermont ski house market runs the same single-season concentration in reverse, a winter peak instead of a summer one, worth comparing for how differently the timing of the concentration plays out. A short season and material participationOnce a property clears the average-stay test, the losses still need material participation to be non-passive: 500 or more hours for the year, substantially all the participation, or 100-plus hours and more than any other individual, including a cleaner, co-host, or property manager. A single-peak market compresses that hour count into a shorter window than a market with steady year-round demand. An owner handling turnovers, maintenance, and guest coordination through a concentrated July season is doing a real share of the year's total work in a matter of weeks rather than spreading it evenly across twelve months. Whether that concentrated stretch adds up to enough hours, and whether it clears whichever material participation test applies, depends on the specific owner's actual time log for the year, not the general shape of the season. Estimate the first-year deduction on a property hereA few questions and the building value give a preliminary first-year deduction range, using the same rule as our free calculator. The breakdown can be emailed to you, or you can book a 15-minute call. Step 1 of 3 What kind of property?
Who runs it day to day?
What is the average guest stay?
When did you buy it?
How many rentals do you own?
Across all of them, does your rental portfolio show taxable income overall?
Any of them likely to sell in the next few years?
Prefer to talk it through? Book straight from here. No form needed.
Docks, ice, and partial asset dispositionLakefront structures like docks and retaining walls take real wear from ice and water exposure over a northern Idaho winter, which means these components get replaced on an actual schedule rather than a hypothetical one. Under Treas. Reg. 1.168(i)-8, when a dock or retaining wall is torn out and rebuilt, the remaining basis of the old component can be written off, but only in the tax year of the replacement. Miss that year and the old component's remaining basis stays on the books for the rest of its recovery period while the new one depreciates separately on top of it. See how partial asset disposition works for the full mechanic. Personal use during the quiet monthsA single-peak lake market often means the owner's own time at the property lands outside the busy July stretch, a shoulder-month weekend rather than competing with peak-season guests for the calendar. Section 280A caps deductions once an owner's personal use exceeds the greater of 14 days or 10% of the days the property is actually rented, and a compressed rental season can make that rented-day count smaller than it would be in a market that books steadily all year. Whether a specific owner's personal-use days cross that line against their actual rented-day total is a question for that owner's CPA, who can run the real count for the year. The process for a Coeur d'Alene propertyThe study runs on the same hands-off process for a lake house or a condo unit: interior and listing photos, the same ones already posted to Airbnb or VRBO, feed the component classification, no site visit and no owner homework list. Every study is custom-priced to the specific property's size, age, and amenity mix, and residential turnaround normally runs 1 to 2 weeks, 2 to 3 weeks during tax season. On a short-term rental, Basis guarantees at least 30 times the fee in first-year deductions, or the study is free. A free Preliminary Benefit Estimate at /qualify models the likely number for a specific property before anyone commits to anything. For the full picture across vacation markets, see the vacation rental markets hub. Frequently asked questionsWhat county is Coeur d'Alene, Idaho in? Coeur d'Alene sits in Kootenai County, Idaho, on the lake of the same name. Spokane, Washington, sits close enough to supply the bulk of the market's drive-to rental traffic. Do docks and boat lifts qualify for faster depreciation? Generally yes. A private dock, boat lift, or buoy system typically falls into the 15-year land improvement bucket rather than the 27.5/39-year schedule the house itself uses. An engineering study evaluates the dock as its own component separate from the structure. How does a single summer peak affect the short-term rental average-stay test? It changes how much weight the off-peak months carry. With July holding the bulk of a property's bookings, the smaller number of stays outside that window can move the yearly average more than they would in a market with steadier year-round demand. The actual result depends on the specific property's full booking record. Is Coeur d'Alene similar to a ski town for tax purposes? The underlying rules are identical, but the timing runs opposite: a ski town like the ones in Vermont concentrates its peak in winter, while Coeur d'Alene concentrates its peak in July. Both are single-season markets that compress a large share of the year's rental activity into one window. What happens if a dock is replaced but partial asset disposition is not claimed that year? The election to write off the old component's remaining basis is only available in the tax year of the replacement. If it is missed, that remaining basis stays on the depreciation schedule for the rest of its recovery period while the new dock depreciates separately on top of it. Keep readingGet your free Preliminary Benefit Estimate Send the address or the listing link. We model the number first; you decide with it in hand. Request Your Free Estimate »Educational information, not tax advice. This page describes how federal
depreciation rules and tests work in general. Whether any rule fits your facts is a determination for
you and your CPA. Our study gives your CPA the engineering and the numbers to make that call.
Related guides: How Does Cost Segregation Work in Vacation... · Does Cost Segregation Work on a Poconos... · Cost Segregation for a Jersey Shore Rental... · Cost Segregation for a Pigeon Forge Cabin... · Cost Segregation for a Gatlinburg Rental...
More Mountain West markets: Does Cost Segregation Work for a Lake Tahoe... · Cost Segregation for a Big Bear Lake Rental... · Does Cost Segregation Work on a Park City... · Cost Segregation for a Breckenridge Rental... · Cost Segregation for a Steamboat Springs... · Does Cost Segregation Work on a Jackson... · All vacation markets
|